Suril Mehta, CA
- Partner, K C Mehta & Co LLP
- Head of the UAE practice, KCM Consultants LLC, Dubai
He advises promoters, family offices and pre-IPO companies on restructuring, relocation and succession across India, the UAE and the US.
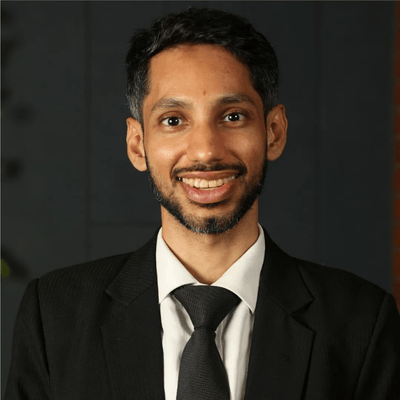
Suril Mehta is a Chartered Accountant and a Partner at K C Mehta & Co LLP, an Indian firm founded in 1958, where he leads the transaction structuring practice. He has been based in Dubai since August 2024 and heads the firm's UAE practice through KCM Consultants LLC.
- Qualification
- Chartered Accountant
- K C Mehta & Co LLP
- Founded in 1958
- Based in Dubai
- Since August 2024
In the UAE almost every restructuring step is free for the shareholder. For the company, the CT reliefs are narrow and each comes with a two-year clawback. Most problems come from a step that is free for the shareholder and still undoes a relief at the company level.
Read the article
What he advises on
Who he advises
- Promoters
- Family offices
- Pre-IPO companies
UAE corporate tax and group restructuring
- Qualifying group relief
- Business restructuring relief
- Tax groups
- Free zone companies
Family foundations, succession and holding structures for families with assets in the UAE and India
Mergers, demergers and transaction structuring in India
Moving promoters and businesses between India, the UAE and the US, including restructuring before an IPO
UAE Tax & Restructuring
A series by Suril Mehta, CA on UAE corporate tax for promoters and family offices: group restructuring reliefs and family foundations, linked to the law.
- UAE Tax & Restructuring · Part 1UAEStructuring and Investment
Restructuring in the UAE: easy for the shareholder, narrow for the company
Most UAE restructuring steps are free for shareholders. Companies get three corporate tax reliefs, each with a two-year clawback. Law as at November 2026.
Suril Mehta16 Nov 2026 · 23 min - UAE-IndiaBusiness Tax
UAE Top-up Tax (Pillar 2) for Indian groups: who must register, by when, and how a deal can bring you in
India has no Pillar 2 rules, but the UAE’s still apply. Who registers, by when, the rupee test, and how mergers and demergers count.
Suril Mehta16 Nov 2026 · 6 min - UAEBusiness Tax
UAE Top-up Tax (Pillar 2) for US groups: who must register, by when, and how a deal can bring you in
USD 850 million is not the test. Who registers for the UAE’s Top-up Tax, by when, and how a deal can bring a US group in.
Suril Mehta16 Nov 2026 · 5 min - UAEBusiness Tax
UAE tax updates, November 2026: e-invoicing penalties, top-up tax and the 31 December deadlines
E-invoicing starts 1 January 2027 with new penalties, top-up tax registration closes 30 November, and five UAE tax deadlines fall on 31 December.
Suril Mehta16 Nov 2026 · 15 min - UAEBusiness Tax
VAT on employee costs: what is recoverable from 1 October 2026
Since 1 October 2026, UAE businesses can recover input VAT on six types of free employee benefits under FTA Decision No. 17 of 2026, if strict conditions are met.
Suril Mehta13 Nov 2026 · 2 min - UAEBusiness Tax
E-invoicing: new penalties, same start date
Cabinet Decision No. 173 of 2026 resets the penalties for e-invoicing breaches in the UAE, ahead of the 1 January 2027 start for businesses with revenue of AED 50 million or more.
Suril Mehta13 Nov 2026 · 2 min - UAEBusiness Tax
UAE Corporate Tax collections reach AED 46.52 billion for 2025
The FTA collected AED 46.52 billion in Corporate Tax for tax periods ending in 2025, up 33.9 per cent, with 91 per cent of returns filed on time.
Suril Mehta13 Nov 2026 · 2 min - UAESuccession Planning and Foundations
DMCC adopts Foundations Regulations: a new option for UAE families
DMCC has adopted Foundations Regulations, making it the fourth place in the UAE, after DIFC, ADGM and RAK ICC, where a family can set up a foundation.
Suril Mehta13 Nov 2026 · 1 min - UAE-IndiaSuccession Planning and Foundations
UAE Family Foundation and GIFT City FIF for Indian Expats
How Indian expats in the UAE can combine a UAE family foundation with a GIFT City Family Investment Fund, and the tax and FEMA caveats.
Suril Mehta and Yog Bakshi11 Nov 2026 · 7 min - UAEBusiness Tax
UAE QFZP Distributors: FTA Decision No. 6 of 2026
FTA Decision No. 6 of 2026 requires an ISRS 4400 agreed-upon procedures report from Designated Zone distributors. Deadlines, worked example and checklist.
Suril Mehta11 Nov 2026 · 12 min - UAE-IndiaStructuring and Investment
Setting Up a FinTech Entity in GIFT City (IFSC)
How to set up a fintech entity in GIFT City IFSC today: the framework, approvals, the current tax holiday and a set-up checklist.
Suril Mehta and Yog Bakshi11 Nov 2026 · 6 min - UAE-IndiaStructuring and Investment
GIFT City AIF vs Offshore Funds for Investing Into India
Comparing a GIFT City AIF with offshore funds for investing into India under the Income-tax Act 2025 and the 20-of-25-year IFSC tax holiday.
Suril Mehta11 Nov 2026 · 6 min - UAE-IndiaStructuring and Investment
DIFC Variable Capital Company for Investing Into India
What a DIFC VCC can and cannot do for investment into India: treaty access, the wholly-managed test, Tiger Global and UAE CT.
Suril Mehta11 Nov 2026 · 7 min - UAE-IndiaStructuring and Investment
UAE Company or Branch for Indian Groups: POEM and Free Zone Risk
Setting up in the UAE from India: company or branch? POEM, treaty residence, the wholly-managed test and the free zone loss risk explained.
Suril Mehta11 Nov 2026 · 11 min - UAE-IndiaStructuring and Investment
Funding a UAE Subsidiary From India: Equity vs Debt
Why equity usually beats debt when an Indian company funds its UAE subsidiary: a debt vs equity vs preference share tax leakage table.
Suril Mehta11 Nov 2026 · 10 min - USSuccession Planning and Foundations
Estate Tax on US Shares: Options for UAE and Indian Investors
Non-US investors pay up to 40% US estate tax above USD 60,000 of US assets. How Indian and UAE families avoid it with blockers, GIFT City funds and Irish ETFs.
Suril Mehta11 Nov 2026 · 10 min - USResidency and Personal Tax
PFIC Tax on Indian Mutual Funds for US-Based NRIs
Why Indian mutual funds are PFICs for US-based NRIs, how the default tax reaches 43%, 52% and 63% of the gain, and what Form 8621 and elections do.
Suril Mehta and Vasu Patel11 Nov 2026 · 10 min - USStructuring and Investment
UAE Holding Company for US Subsidiaries: The Treaty Gap
With no US-UAE income tax treaty, US dividends and interest to a UAE holding company face 30% withholding. The gap, the capital gains upside and the fixes.
Suril Mehta20 Jun 2026 · 7 min
Family foundations, in four parts
- UAE Foundations Series · Part 1 of 4UAEStructuring and Investment
Same property, two tax bills
Rent and investment income sit outside UAE corporate tax for individuals but are taxed at 9% in a company. Why the gap exists and the bridge the law provides.
Suril Mehta16 Nov 2026 · 6 min - UAE Foundations Series · Part 2 of 4UAESuccession Planning and Foundations
How a UAE foundation closes the gap
When a DIFC, ADGM or RAK ICC foundation and the company under it can be treated as transparent for UAE corporate tax, and the condition that most often fails.
Suril Mehta16 Nov 2026 · 7 min - UAE Foundations Series · Part 3 of 4UAESuccession Planning and Foundations
Getting the assets in is where the tax sits
Who owns the asset today decides the tax on moving it into a UAE family foundation. Three starting points, and why company-held property is the hard case.
Suril Mehta16 Nov 2026 · 7 min - UAE Foundations Series · Part 4 of 4UAESuccession Planning and Foundations
Seven questions before you move anything
A short self-check for families considering a UAE foundation for property and investments, including when corporate tax gives you no reason to move anything.
Suril Mehta16 Nov 2026 · 6 min
“These are the questions I would want answered in a first meeting, and they are also the questions you should put to whoever advises you, ourselves included.”
Arrange a conversation
Tell us briefly what you are dealing with, and the right advisor will come back to you.
Arrange a conversation- linkedin.com/in/surilm
- Office
- Office 3001A, Al Saqr Business Tower, Trade Centre Second, Dubai