UAEBusiness Tax
VAT on employee costs: what is recoverable from 1 October 2026
By Suril Mehta, CA, Partner, K C Mehta & Co LLP | KCM Consultants LLC, Dubai
Published 13 November 20262 min
What the decision says
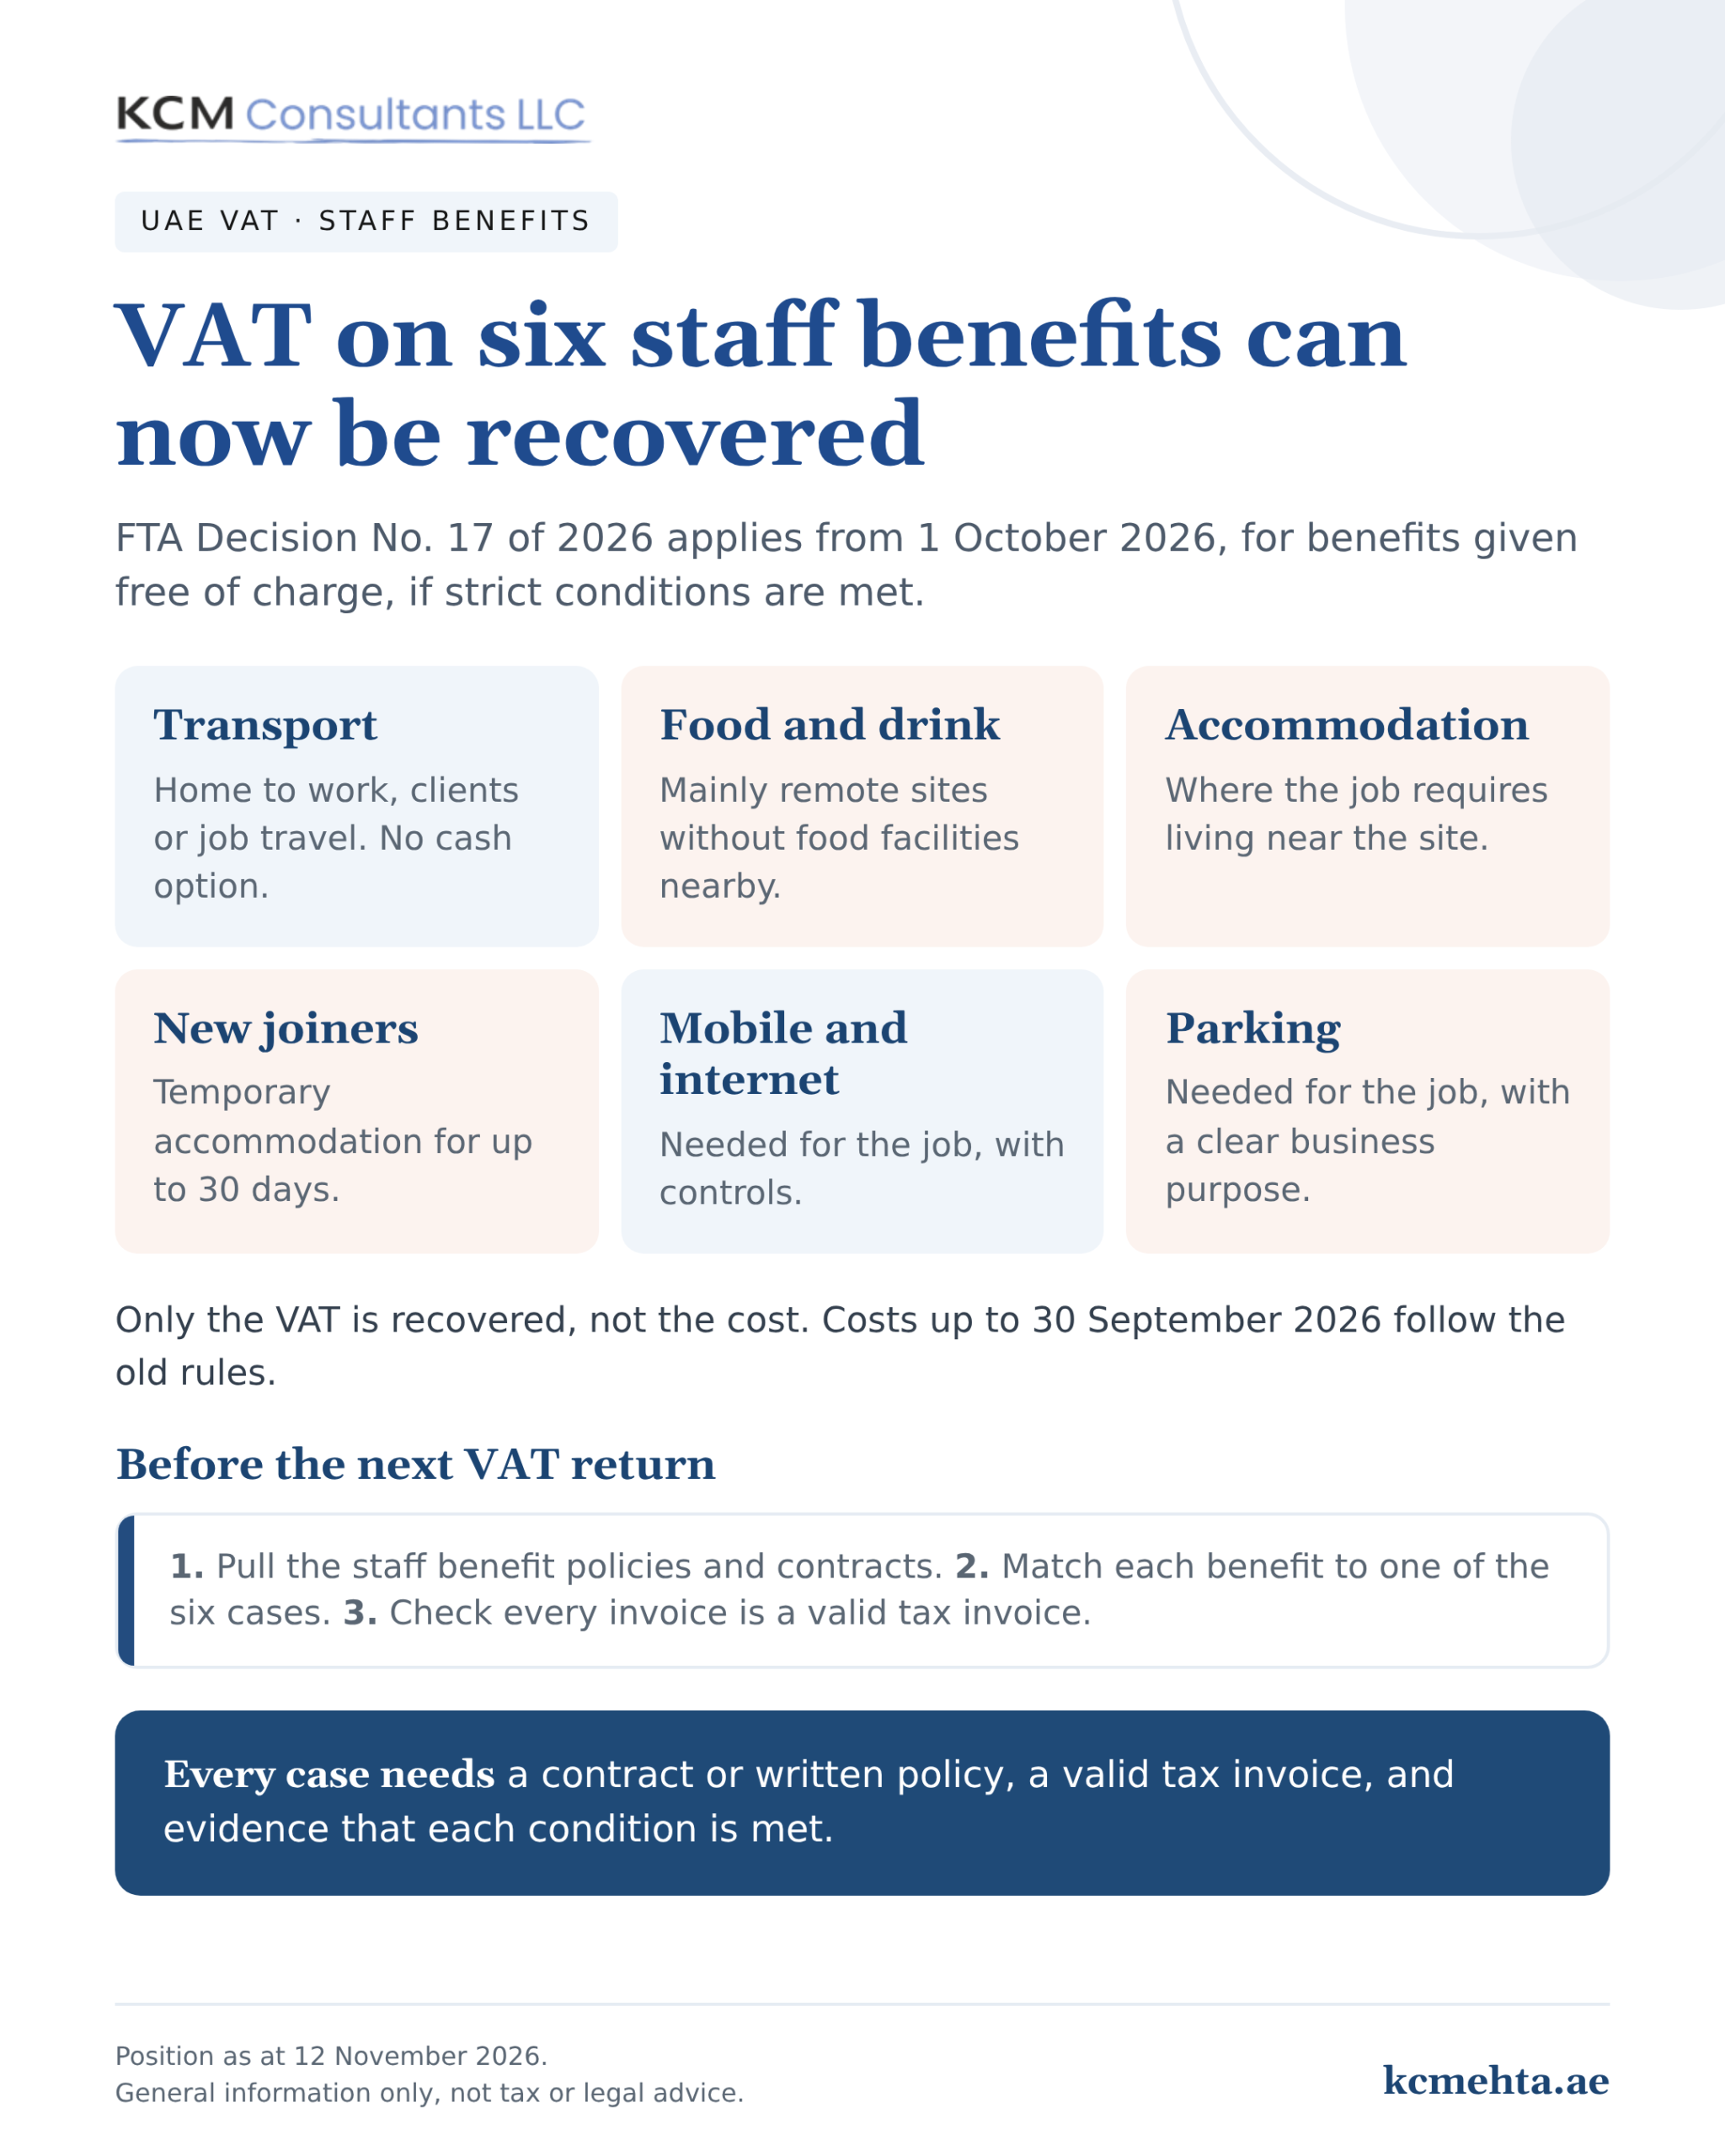
FTA Decision No. 17 of 2026, issued on 9 September 2026 and effective from 1 October 2026, allows a VAT-registered business to recover input tax on six types of employee costs provided free of charge. Recovery applies only where a contract or documented policy requires the benefit and every condition for that case is met.
The six cases
| Category of expense | Conditions for VAT recovery |
|---|---|
| Transport | Home to work, to client premises or for job duties only. No personal use. No cash alternative. |
| Food and beverages | Remote or isolated location with no kitchen or nearby food outlets. Linked to the work period. No cash alternative. |
| Accommodation | Required by the work and not part of regular pay. For the employee only, unless the employee must live there permanently. Suited to the role and basic living needs. No cash alternative. |
| New joiners | Temporary accommodation for up to 30 days, suited to the role. |
| Mobile and internet | Needed for work. Personal use only incidental. Written usage policy and reasonable monitoring. |
| Parking | Business purposes only. Written reimbursement policy. Receipts kept. |
What every claim needs
- A contract or documented policy requiring the benefit
- A valid tax invoice
- Records showing that each condition is met
What to do now
Before your next VAT return, map employee costs against the six cases and ensure every benefit is backed by a contract or written policy. For phones, internet and parking, the policy must also set out permitted use, approvals and monitoring. Remove cash alternatives where VAT is being claimed and keep the evidence file by case. Benefits that are mainly personal, or that come with a cash option, are unlikely to qualify.
KCM Consultants can review staff benefit policies and VAT positions against the decision. To discuss, contact Suril Mehta at Suril.mehta@kcmehta.com.
Source: FTA Decision No. 17 of 2026.
Disclaimer: General information only, not tax or legal advice. Position as at 16 November 2026.
Related
- UAEBusiness Tax
UAE tax updates, November 2026: e-invoicing penalties, top-up tax and the 31 December deadlines
E-invoicing starts 1 January 2027 with new penalties, top-up tax registration closes 30 November, and five UAE tax deadlines fall on 31 December.
Suril Mehta16 Nov 2026 · 15 min - UAEBusiness Tax
E-invoicing: new penalties, same start date
Cabinet Decision No. 173 of 2026 resets the penalties for e-invoicing breaches in the UAE, ahead of the 1 January 2027 start for businesses with revenue of AED 50 million or more.
Suril Mehta13 Nov 2026 · 2 min