UAEBusiness Tax
UAE Top-up Tax (Pillar 2) for US groups: who must register, by when, and how a deal can bring you in
By Suril Mehta, CA, Partner, K C Mehta & Co LLP | KCM Consultants LLC, Dubai
Published 16 November 20265 min
This version is for US groups with companies or branches in the UAE. For Indian groups, see the version for Indian groups, with the rupee test, the April to March year and Indian demergers.
In short
Neither group ever had EUR 750 million in revenue. After one acquired the other, the UAE’s Pillar 2 rules treat them as if they had, and every UAE company of the combined group has to register for the UAE’s 15% Top-up Tax. For a calendar-year group, the last date is 30 November 2026.
- It is a separate registration. The Corporate Tax registration does not cover it, and it is needed even where no Top-up Tax is payable.
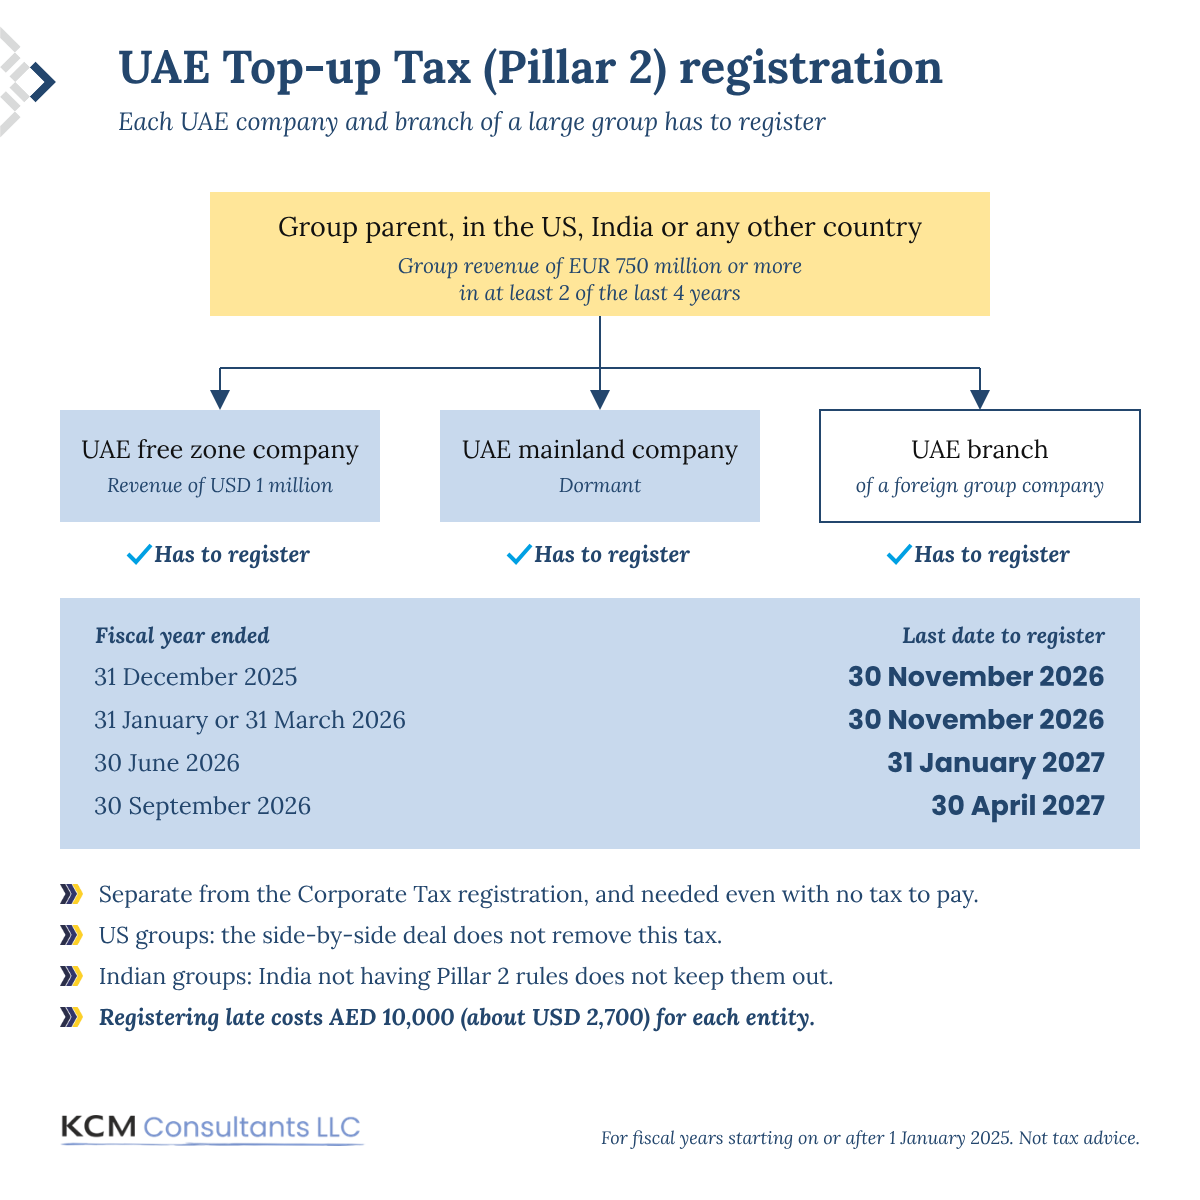
- The group is tested, not the UAE company. A UAE company with revenue of USD 1 million is within it if its group is.
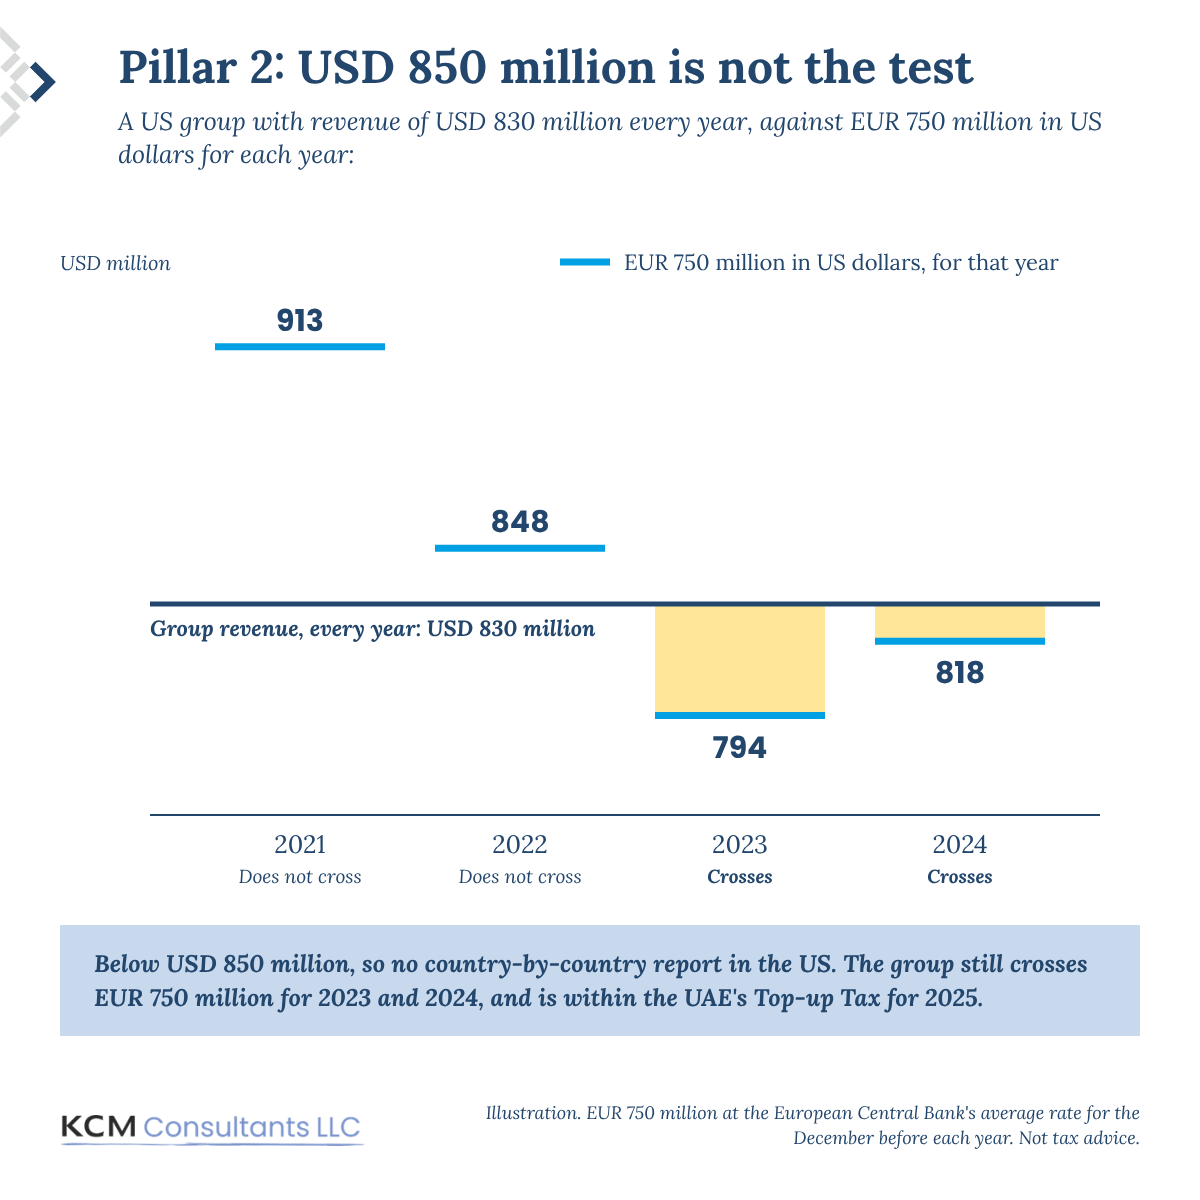
- USD 850 million is not the test. That is the US mark for country-by-country reporting. A group at USD 830 million a year can still be in.
- The side-by-side deal does not help here. It covers the charges other countries levy on a US group’s profits, not the UAE’s own tax on UAE profits.
- A deal can change the answer. An acquisition, merger, spin-off or split-off in the last 4 years can bring in a group whose own accounts never crossed EUR 750 million.
- Missing the date costs AED 10,000 (about USD 2,700) for each UAE entity.
This note is for CFOs, tax heads and owners of US groups with a company or a branch in the UAE. It covers who has to register, by when, the dollar trap, how a deal changes the test, and what to keep ready.
Is your group in? Five questions
If any answer puts the group in, every UAE company and branch of the group has to register.
- Is the group multinational? It needs at least one company or branch outside the country of its ultimate parent. A US group with a UAE company already is.
- Did consolidated revenue reach EUR 750 million in at least 2 of the 4 years before the year being tested? For 2025, those years are 2021 to 2024.
- Did the group acquire, or merge with, another group in those years? Then add the other group’s revenue for each year before the deal, and test again.
- Did the group come out of a spin-off or split-off (a demerger) of a group that was in? Then look at its own revenue in the first year ending after the separation.
- Does the group report in US dollars? Convert EUR 750 million at the December rate before each year being looked at. Not at today’s rate, and not USD 850 million.
How the EUR 750 million test works
The Top-up Tax is the UAE’s version of the 15% global minimum tax under Pillar 2. It applies for years starting on or after 1 January 2025, to the UAE companies and branches of a multinational group whose revenue was EUR 750 million or more in at least 2 of the 4 years before the year being tested.
- The revenue is the group’s. It is taken from the consolidated accounts of the ultimate parent, wherever that parent is. The UAE company’s own size does not matter.
- The test runs every year. For 2025 it looks at 2021 to 2024; for 2026, at 2022 to 2025. A group can come in, and go out, as its revenue moves.
- A short year is scaled. Where a year is not 12 months, the EUR 750 million is reduced in proportion.
- The group must be multinational. A group with all its companies in the UAE is outside. One subsidiary or branch abroad, or a foreign parent, changes that.
This may be highly non-intuitive, but the figures used for the test are not always the figures in your accounts. The dollar value of the test changes every year, and after an acquisition, merger, spin-off or split-off, the law adjusts the revenue history. The sections below show how.
The dollar trap: USD 850 million is not the test
US groups know USD 850 million as the mark for the country-by-country report (IRS Form 8975). The Top-up Tax test is EUR 750 million, converted afresh for each year at the European Central Bank’s average rate for the December before that year.
| Year | Rate used (USD per EUR, December before) | EUR 750 million in USD |
|---|---|---|
| 2021 | 1.2170 (December 2020) | about USD 913 million |
| 2022 | 1.1304 (December 2021) | about USD 848 million |
| 2023 | 1.0589 (December 2022) | about USD 794 million |
| 2024 | 1.0903 (December 2023) | about USD 818 million |
A US group with revenue of USD 830 million every year files no country-by-country report in the US. For the Top-up Tax it crossed EUR 750 million for 2023 and 2024, so it is in for 2025. With a calendar year, its UAE companies register by 30 November 2026.
The side-by-side deal does not take the UAE’s tax away. Under the OECD’s side-by-side package of January 2026, US-parented groups can opt out of the income inclusion rule and the undertaxed profits rule: the charges one country levies on profits made in another. A country’s own top-up tax on profits made within it was left as it is, and the UAE’s is one. A US group’s UAE companies still register.
If Top-up Tax is payable in the UAE, check with your US tax team how it sits with the US tax on the income of foreign subsidiaries.
Who has to register
If the group is in, each of its UAE entities registers on its own, on the Federal Tax Authority’s (FTA) EmaraTax portal. The common surprises are below.
| UAE entity of an in-scope group | Has to register? | Why it is missed |
|---|---|---|
| Mainland company | Yes | Its own revenue may be small |
| Free zone company paying 0% | Yes | No tax is paid, so it looks out of scope |
| Dormant company | Yes | It does no business, but it is still a group company |
| Branch of a foreign group company | Yes | It is not a separate company |
| Joint venture | Yes, on its own, as per the FTA’s guide | It may not be consolidated line by line |
- The Corporate Tax registration does not cover it. This is a separate registration, with its own number.
- No tax to pay does not mean no registration. A group whose UAE profits already bear 15% or more, or which falls in a safe harbour, still registers.
As per the FTA’s guide on scope and registration, a penalty of AED 10,000 (about USD 2,700) applies for each entity that does not register in time.
The dates
Each UAE entity registers within 7 months after the end of the group’s first year in scope. Where that year ended before 30 April 2026, the last date is 30 November 2026.
| Group’s year ends on | First year in scope | Last date to register |
|---|---|---|
| 31 December (most US groups) | 1 January to 31 December 2025 | 30 November 2026 |
| 31 January | 1 February 2025 to 31 January 2026 | 30 November 2026 |
| 31 March | 1 April 2025 to 31 March 2026 | 30 November 2026 |
| 30 June | 1 July 2025 to 30 June 2026 | 31 January 2027 |
| 30 September | 1 October 2025 to 30 September 2026 | 30 April 2027 |
The same 7-month rule applies later on:
- A group that comes in for a later year registers within 7 months after the end of that year.
- A UAE company that joins an in-scope group, for example on an acquisition, registers within 7 months after the end of the year in which it joins.
- A UAE entity that is closed, or leaves the group, deregisters within 6 months. For one that ceased before 30 June 2026, the date is 31 December 2026. The FTA does not deregister an entity until its tax, penalties and returns are settled.
Deals that change the answer
If your group did an acquisition, merger, spin-off or split-off in the last 4 years, do not go by its consolidated revenue alone. Run the test again with the deal in it.
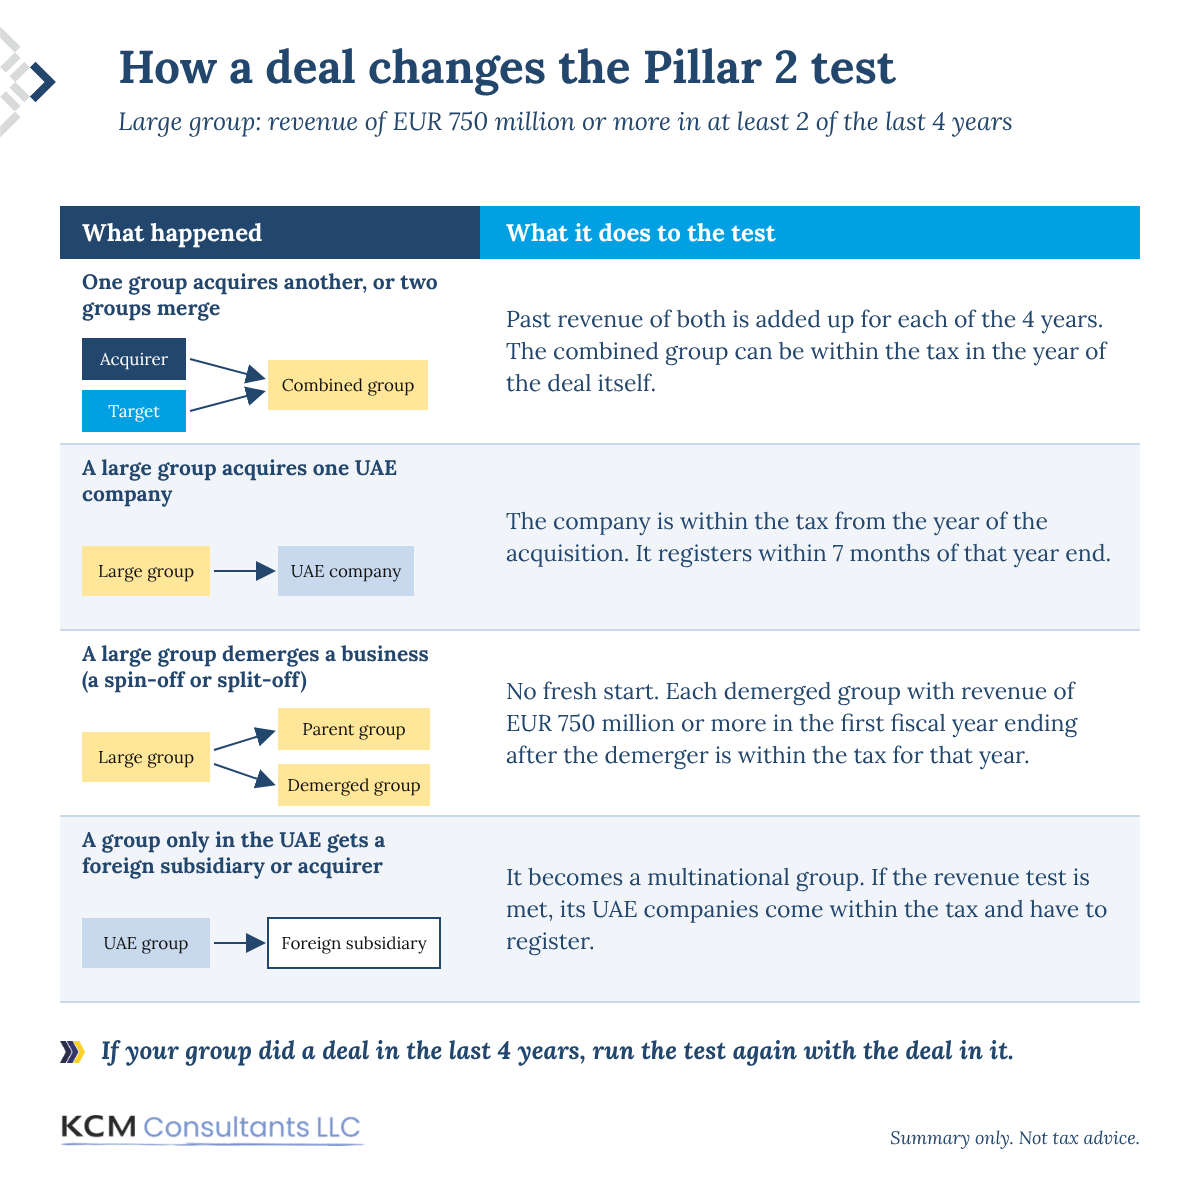
An acquisition or merger of two groups
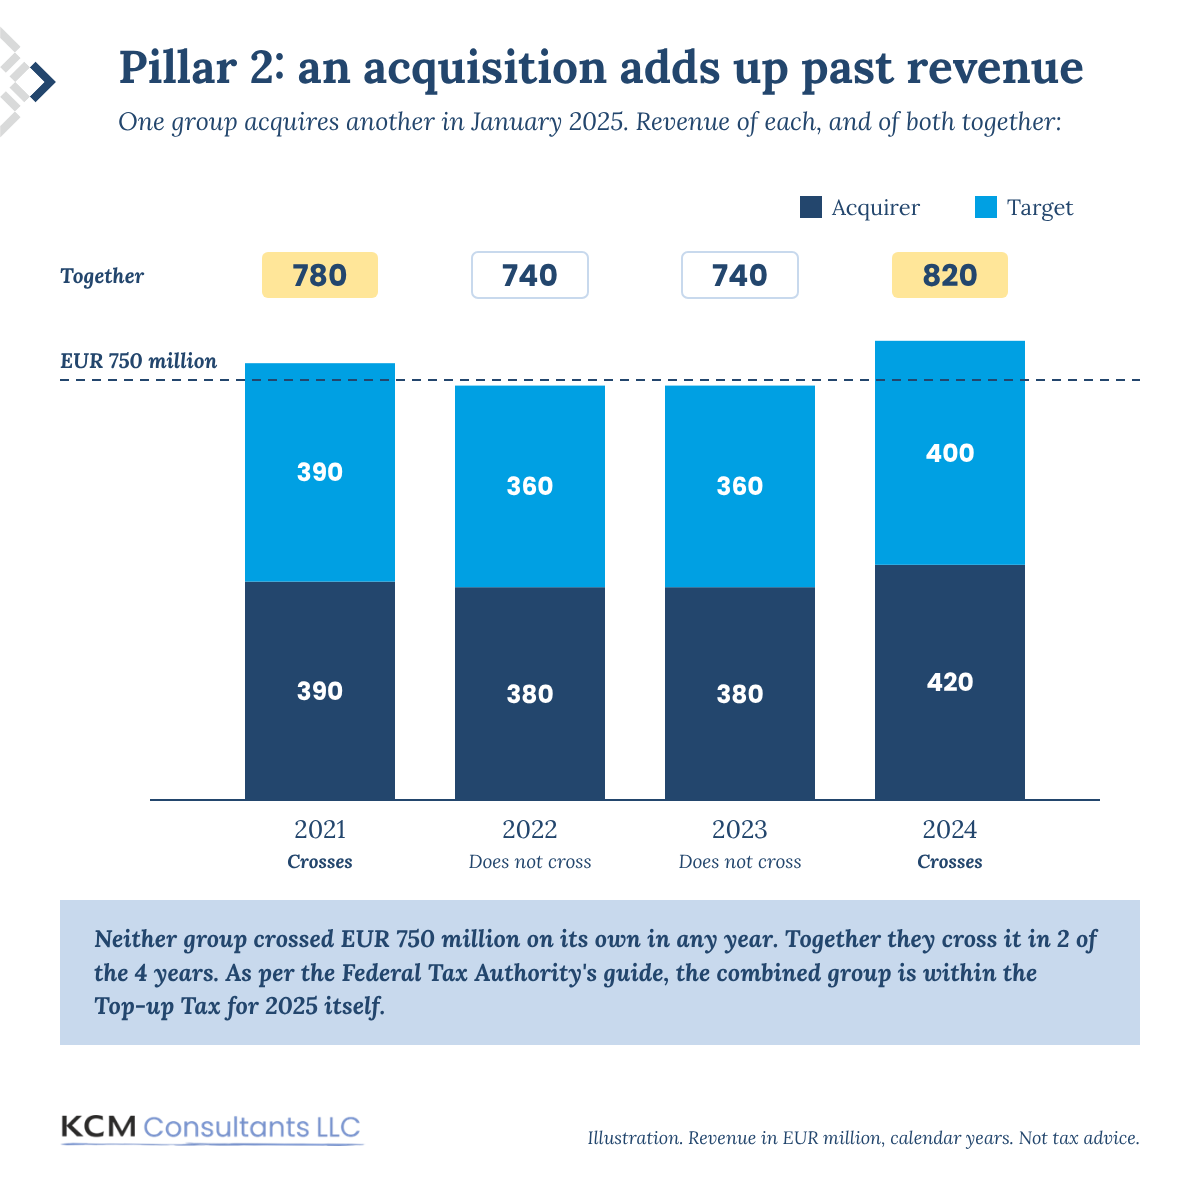
For each year before the deal, the revenue of BOTH groups is added up, as if they had always been one group. In your accounts, the target’s revenue comes in only from the closing date. For this test, it counts for the earlier years as well.
| Year | Acquirer (EUR million) | Target (EUR million) | Together (EUR million) | EUR 750 million crossed? |
|---|---|---|---|---|
| 2021 | 390 | 390 | 780 | Yes |
| 2022 | 380 | 360 | 740 | No |
| 2023 | 380 | 360 | 740 | No |
| 2024 | 420 | 400 | 820 | Yes |
Neither group crossed EUR 750 million on its own. One acquires the other in January 2025. Together they crossed it in 2 of the 4 years, so as per the FTA’s guide, the combined group is in for 2025, the year of the deal itself.
Keep in mind 2 things:
- The FTA’s guide applies this even where the deal falls in the year being tested. The Cabinet Decision speaks of a merger in one of the 4 earlier years, so a deal in the tested year deserves a second look.
- The rule is written for two groups coming together. Buying only part of another group, such as one of its subsidiaries, is not a merger for this rule: that business counts only from when it is consolidated.
Acquiring one UAE company
A UAE company acquired by an in-scope group is in from the year of the acquisition. It registers within 7 months after that year ends: for a calendar-year group that acquires it in 2026, by 31 July 2027.
A spin-off or split-off (a demerger)
The law calls it a demerger: one group separating into two or more groups that are no longer consolidated by the same parent. In the US, that is usually a spin-off or a split-off. A group that was in does not get a fresh start:
- First year after the separation. Each separated group is in if its revenue for the first year ending after the separation is EUR 750 million or more.
- Second to fourth years. Each is in if its revenue was EUR 750 million or more in at least 2 of the years after the separation.
Moving a business into a new subsidiary under the same parent is not a demerger for this rule, and nor is a carve-out IPO where the parent keeps control. The group stays one group.
A group only in the UAE becomes multinational
A group with all its companies in the UAE is outside, however large. It becomes multinational when it sets up or buys a company or branch abroad, or when a foreign group acquires it. As per the FTA’s guide, a UAE group acquired by a foreign company in 2025 can be in for 2025 itself.
After registration
Registration is the first step. The first Top-up Tax return is due 18 months after the end of the first year in scope, and 15 months after the year end for later years: for a calendar-year group, 30 June 2027 for 2025.
What to keep ready now:
- Consolidated revenue for the last 4 years, adjusted for any acquisition, merger, spin-off or split-off.
- A list of every UAE company, branch and joint venture of the group, with its licence and Corporate Tax number.
- The group chart up to the ultimate parent.
- For the return: the UAE accounts, the taxes paid, and the payroll and assets in the UAE, which reduce the profit that can be topped up.
How we can help
We work across the UAE, the US and India, so we see these groups from both ends: the US parent’s accounts and the UAE companies.
- Confirm scope. We run the EUR 750 million test for each year, with your acquisitions, mergers, spin-offs and split-offs in it, at the right exchange rates.
- Register each UAE entity. Companies, branches and joint ventures, before your last date.
- Plan the first return. We map the data the return needs, so the 2027 filing is not a scramble.
Write to connect@kcmehta.ae, or see our UAE Corporate Tax Advisory and Transaction Structuring services.
We are hiring in Dubai and India for UAE corporate tax, audit, succession planning and business development. See Careers.
Questions we are being asked
Our UAE company has revenue of only AED 2 million. Does it still have to register? Yes, if its group is in. The test looks at the group’s revenue, not the UAE company’s.
We are below USD 850 million and file no country-by-country report. Are we out? Not necessarily. The test is EUR 750 million at each year’s December rate: about USD 794 million for 2023 and USD 818 million for 2024.
We are a US group. Doesn’t the side-by-side deal cover us? No. It covers the charges other countries levy on a US group’s profits. The UAE’s own top-up tax on UAE profits stays.
We already have a Corporate Tax registration. Is that enough? No. The Top-up Tax registration is separate.
We expect to pay no Top-up Tax. Do we still register? Yes. Registration does not depend on tax being payable.
Our group never crossed EUR 750 million, but we acquired another group in 2023. Could we be in? Yes. The two groups’ revenue is added up for each year before the deal. Run the test with both.
We spun off a business in 2024. Does the new group start afresh? No. If the group was in, each separated group with revenue of EUR 750 million or more in its first year ending after the spin-off is in for that year.
What does it cost to miss the date? AED 10,000 (about USD 2,700) for each UAE entity, as per the FTA’s guide.
Related reading
- UAE Top-up Tax (Pillar 2) for Indian groups: the same rules, with the rupee test and Indian demergers
- 31 December: five UAE tax deadlines fall on one day
- Pillar One and Pillar Two: strengthening the foundation
References
- Cabinet Decision No. 142 of 2024 on the Top-up Tax: Article 1.1 for the EUR 750 million test, Article 6.1 for mergers and demergers.
- FTA Decision No. 12 of 2026 on registration dates (KPMG summary).
- FTA guide on Top-up Tax scope and registration (TTGREG1).
- OECD side-by-side package, January 2026 (Loyens & Loeff summary).
- IRS instructions for Form 8975, country-by-country reporting.
- Exchange rates: European Central Bank reference rates, December monthly averages (Banque de France, December 2023).
Current as at 16 November 2026. This note is general information, not tax advice.
Related
- UAE-IndiaBusiness Tax
UAE Top-up Tax (Pillar 2) for Indian groups: who must register, by when, and how a deal can bring you in
India has no Pillar 2 rules, but the UAE’s still apply. Who registers, by when, the rupee test, and how mergers and demergers count.
Suril Mehta16 Nov 2026 · 6 min - UAEBusiness Tax
UAE tax updates, November 2026: e-invoicing penalties, top-up tax and the 31 December deadlines
E-invoicing starts 1 January 2027 with new penalties, top-up tax registration closes 30 November, and five UAE tax deadlines fall on 31 December.
Suril Mehta16 Nov 2026 · 15 min