UAESuccession Planning and FoundationsUAE Foundations Series
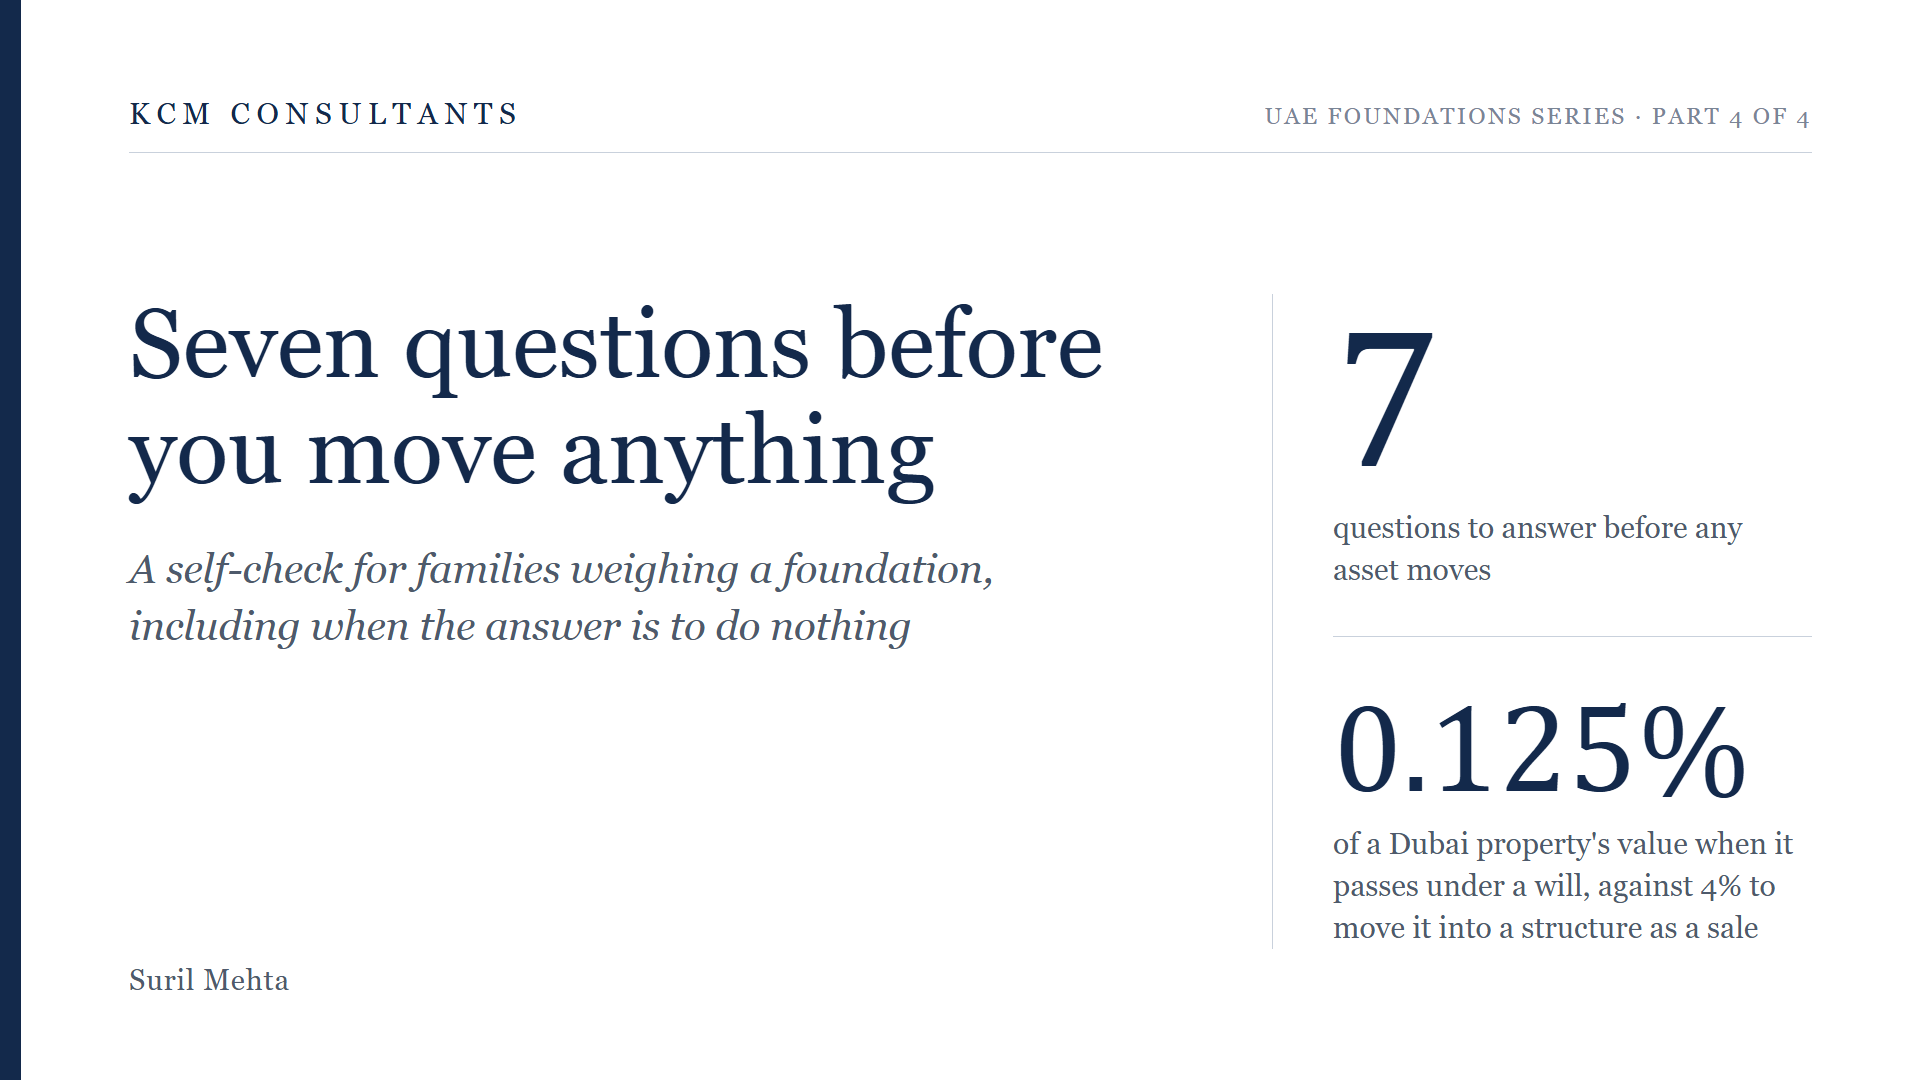
Seven questions before you move anything
A self-check for families weighing a foundation, including when the answer is to do nothing
By Suril Mehta, CA, Partner, K C Mehta & Co LLP | KCM Consultants LLC, Dubai
Published 16 November 20266 min
The first three parts of this series covered what the law allows. This one is about your own position, before anyone draws a structure. These are the questions I would want answered in a first meeting, and they are also the questions you should put to whoever advises you, ourselves included.
The seven questions
Who will the beneficiaries be?
Only identified or identifiable individuals, and public benefit entities, qualify. A company as a beneficiary does not work. If a charity is on the list, its share of any income that would be taxable in its own hands has to be paid out to it within 6 months of the year end.
Would the activity need a licence if you did it yourself?
Renting out flats doesn’t. Running a hotel, letting holiday homes under your own DET (Department of Economy and Tourism) permit or trading does. If the answer is yes, whichever entity carries on that activity, the foundation itself or a company under it, stays taxable on all its income.
Who owns the asset today?
You, your UAE company, or a company abroad. Each leads to a different bill, as Part 3 showed. A foreign company that earns income from UAE property is already within UAE corporate tax on that income and has to register (Cabinet Decision 35 of 2025). A foundation set up abroad that holds UAE property can also apply to be treated as see-through, not only a UAE one. And for Dubai property, check that the vehicle you choose can hold title there before you set it up.
Where do you and your family live for tax?
The UAE answer can be zero while the home-country answer isn’t. South Africa, for example, can tax a resident each year on the profits of a UAE company they control, because 9% is well below its threshold for exempting low-taxed foreign companies. Tax on the transfer itself (capital gains, gift or donations tax) and look-through rules for foundations are the other two to check before anything moves.
How large is the built-up gain, and when did it start?
If your company has to move the asset itself, this decides what it costs. The foundation or its company will be a related party, so your company is treated as selling at market value and pays 9% on the gain. Gains from before the company’s first tax period can be left out, but only if the property was carried at cost in its accounts and the company made that election in its first return.
Is any property let commercially?
VAT (value added tax) is a separate tax and doesn’t follow corporate tax (CT) transparency. Residential leases are generally exempt; commercial leases carry 5%, and whichever entity is the landlord stays responsible for VAT on it, and has to register once its taxable supplies pass AED 375,000 a year.
What is the reason, other than tax, that you would give if asked?
Succession, holding as a family, keeping assets together after a death, governance. The FTA (Federal Tax Authority) says applying for transparency is not in itself a tax avoidance purpose. But its real estate guide also says that if an arrangement is made mainly to get the real estate exclusion (the rule that keeps an individual’s rent outside CT) and lacks commercial substance, the FTA can treat the income as taxable anyway. The general anti-abuse rule in Article 50 sits over all of it. Write that reason down before you start.
When the answer is to do nothing
Sometimes the right answer is to do nothing. If you are UAE resident and hold residential property in your own name, CT gives you no reason to move it. A foundation may still make sense for succession, but that is a different conversation. In Dubai, when property passes under a will, the land department charges 0.125% of its value to register the transfer, and AED 1,000 a property to register heirs. Moving the same property into a structure now costs 4% if it is registered as a sale, or 0.125% at best if the land department accepts it as a gift, before the cost of setting up and running a foundation. For many families a registered will does most of the job for less.
That closes this series.
If one of these seven doesn’t have a clear answer for you today, that is usually the place to start.
How KCM can support
KCM Consultants LLC works with families on whether a foundation fits, and on the tax position before, during and after assets move.
Where you stand today
A review of what you hold personally and through companies, where the family is resident for tax, and what each holding costs under UAE corporate tax today.
Transparency, applied for and kept
Corporate tax registration for the foundation and each company under it, the Article 17 application on EmaraTax, and the annual confirmation that keeps the status.
Moving assets in
The corporate tax, land department and VAT position on each transfer, coordinated with advisers in your home country, before anything moves.
References
- UAE Ministry of Finance, Federal Decree-Law No. 47 of 2022 on the Taxation of Corporations and Businesses, with amendments (consolidated text, January 2026) (Articles 17, 34 and 50).
- UAE Ministry of Finance, Cabinet Decision No. 35 of 2025 on a non-resident person's nexus in the State.
- UAE Ministry of Finance, Ministerial Decision No. 261 of 2024 on Unincorporated Partnership, Foreign Partnership and Family Foundation.
- UAE Ministry of Finance, Ministerial Decision No. 120 of 2023 on adjustments under the transitional rules.
- Federal Tax Authority, Taxation of Family Foundations, Corporate Tax Guide CTGFF1 (June 2026).
- Federal Tax Authority, Real Estate Investment for Natural Persons, Corporate Tax Guide CTGREI1.
- Government of Dubai, Executive Council Resolution No. (30) of 2013 Approving Fees of the Land Department.
- Dubai Land Department, Real estate inheritance registration (fees).
- Dubai Land Department, Property sale registration.
- Dubai Land Department, Property gift registration.
Related
- UAE Foundations Series · Part 3 of 4UAESuccession Planning and Foundations
Getting the assets in is where the tax sits
Who owns the asset today decides the tax on moving it into a UAE family foundation. Three starting points, and why company-held property is the hard case.
Suril Mehta16 Nov 2026 · 7 min - KCM HeirloomUAESuccession Planning and Foundations
UAE Foundations: A Structured Approach to Asset Management & Succession
A practical guide to UAE foundations across ADGM, DIFC, and RAK ICC — participants, probate and tax effects, forced heirship protection, and jurisdiction comparison.
Rachaita Warriar20 Jun 2026 · 11 min